How the 2025 tax bill affects your taxes

Plain-language financial writing since 2012

Keep calm. Stay invested. Build lasting wealth.

Independent financial writing for high-earning professionals navigating RSUs, taxes, markets, and the noise in between. Written by Nirav Desai, founder of Qubera Wealth Management.

Book a Free Consultation →

This newsletter comes from the tropical Grand Cayman islands in the Caribbean. I’m sitting next the the beach, with its white sands, and turquoise waters. It’s 90 degrees with 90% humidity, and I’m slathered with SPF 50!

But there have been some major updates in the tax code that can’t wait, so I wanted to provide a simplified version of how the 900 page bill impacts you.

The One Big Beautfiul Bill Act (OBBA), signed on July 4, 2025, is officially named the Omnibus Budget Reconciliation Act of 2025, and it contains sweeping changes that will impact your taxes, investments, healthcare, and estate plans.

The primary goals of this act were to make many provisions of the 2017 Tax Cuts and Jobs Act (TCJA) permanent while also introducing a new set of economic priorities. Understanding these shifts now is crucial for proactive financial planning.

The following are the most critical changes to note:

1. Permanent Changes to Individual Taxes

A major function of this bill was to prevent the widespread tax increases that would have occurred if key parts of the TCJA had expired. The following are now permanent law:

  • Individual Tax Rates: The lower individual income tax rates from the TCJA are here to stay, providing long-term certainty for income and retirement planning. The top rate remains at 37% instead of reverting back to 39.6%.
  • Higher Standard Deduction: The larger standard deduction is now permanent. For 2025, it is set at $31,500 for married couples filing jointly and $15,750 for single filers, adjusted for inflation annually.
  • The 20% QBI Deduction: The crucial 20% deduction on Qualified Business Income (Section 199A) for pass-through businesses (S-corps, partnerships, sole proprietorships) has been made permanent, a significant victory for entrepreneurs. This includes REIT dividends, as well as interest income from certain types of Real Estate Loans (including the fund we own in client portfolios).
  • Estate Tax Exemption: The act permanently sets the estate and gift tax exemption at a $15m and $30m for married couples, effectively eliminating federal estate tax concerns for most families. Without this change, it was set to revert back to the lower level of approximately $4m and $8m.

2. New (and Temporary) Tax Breaks for Individuals

The Act introduces several new, targeted tax deductions. It is critical to note that most of these are temporary and are set to expire after 2028.

  • No Tax on Tips & Overtime: For tax years 2025 through 2028, deductions are available for qualified tip income (up to $25,000) and for the premium portion of overtime pay (up to $12,500 for single filers, $25,000 for joint filers). Both deductions are subject to income phase-outs.
  • Additional Deduction for Seniors: Individuals aged 65 and older receive a new temporary bonus deduction of $6,000, which also phases out at higher income levels.
  • Auto Loan Interest Deduction: A temporary deduction is available for interest paid on loans for new passenger vehicles where final assembly occurred in the United States. This is limited to $10,000 per year and is subject to income limitations.

3. Major Changes to Healthcare and the SALT Deduction

  • SALT Cap Relief: In a significant but temporary change, the State and Local Tax (SALT) deduction cap is increased from $10,000 to $40,000 for taxpayers with income below $500,000. This higher cap is effective for tax years 2025 through 2029, after which it reverts to $10,000. This creates a critical multi-year window for strategic tax planning for those in high-tax states.
  • This deduction phases out for a married-filing-jointly (MFJ) with income between $500k and $600k, beyond which it drops down to $10,000. For each dollar of income over $501k, you lose 30 cents of the deduction. This creates a weird situation,  where $1 of income increases taxable income by $1.30. This pushes the marginal tax rate to 45.5% between $501k and $600k for anyone who itemizes, either due to high property or state taxes, a high interest mortgage, or large charitable contributions. If you have interest income that falls in this income range, you will also owe 3.8% NIIT, pushing your marginal tax bracket to 49.3%. For these high income earners, critical tax planning can have an outsized impact on lowering taxes.
  • Healthcare & Medicaid: The law enacts significant long-term spending cuts to Medicaid and reduces Affordable Care Act (ACA) subsidies. It also introduces work requirements for certain Medicaid recipients and makes changes to eligibility for some immigrant populations. These changes could increase out-of-pocket healthcare costs for many, negatively impacting your financial planning goals.

4. Business and Energy Tax Overhaul

  • Bonus Depreciation Restored: For business owners, the act permanently restores 100% bonus depreciation for qualified property, a powerful incentive to invest in new equipment and other assets. This will allow for outsized deductions for small business owners as well.
  • Repeal of Green Energy Credits: The law repeals several popular Inflation Reduction Act (IRA) tax credits aimed at individuals, including those for new and used electric vehicles (EVs) and residential clean energy projects. The financial calculations for making these purchases have now fundamentally changed. If you were planning on adding solar panels to your roof or buying an EV, your window to make the purchase and get a tax credit is very small!

Your Path Forward: Navigating the New Landscape

This new legislation creates a complex environment of permanent tax certainty, temporary opportunities, and significant policy shifts. The temporary nature of the new deductions and the expanded SALT cap creates a critical window where proactive planning can yield substantial benefits.

I advise all high-income clients to schedule a dedicated strategy session with me to:

  • Analyze how these permanent and temporary changes impact your specific financial picture.
  • Develop a multi-year strategy to take full advantage of the temporary SALT cap relief.
  • Review your business and estate plans in light of the new rules.

Please use this link to schedule a time for us to connect.
{ 0 comments }

The Qualified Opportunity Zone (QOZ) program is undergoing significant changes, primarily driven by proposed legislation like the “One Big Beautiful Bill Act” (OBBBA) in the US Congress. While some details may vary between the House and Senate versions, here’s a summary of the key new rules and proposed changes:

  1. Permanence and Re-designation of Zones:
  • Permanent Program: The QOZ program is expected to become a permanent fixture, eliminating the previous sunset date for new investments (originally December 31, 2026).
  • Decennial Re-designation: New QOZs will be designated every 10 years, starting July 1, 2026, with effective dates for investments beginning January 1, 2027. This means states will propose new zones, and the Treasury Secretary will certify them, ensuring the program continues to target areas of need.
  • Stricter Eligibility: The criteria for designating “low-income communities” are becoming stricter. The median family income threshold for a tract to qualify is expected to drop from 80% to 70% of the area or statewide median. The provision allowing contiguous non-low-income tracts to be designated is also likely to be eliminated.
  1. Investment Deferral and Basis Step-Up:
  • Extended Deferral: For investments made after December 31, 2026, the deferral of capital gains tax will be extended, with a rolling five-year deferral period. This means the deferral will no longer be tied to a fixed date like December 31, 2026, but will be five years from the date of investment.
  • New Basis Step-Up Schedule: The current 10% basis step-up after five years and 15% after seven years will be revised. For investments made after December 31, 2026, a 10% basis step-up will be available after five years.
  • Ordinary Income Investments: A significant new allowance is the deferral of up to $10,000 of ordinary income invested in a Qualified Opportunity Fund (QOF) after December 31, 2026.
  1. Emphasis on Rural Zones:
  • Rural QOZ Set-Aside: A notable change is the push to designate more rural QOZs. At least 33% of new QOZs are expected to be in rural areas.
  • Enhanced Rural Benefits: Investments in “Qualified Rural Opportunity Funds” (QROFs) will receive additional incentives:
  • Increased Basis Step-Up: A 30% basis step-up will be available for qualified rural investments held for at least five years, significantly higher than the 10% for other QOZ investments.
  • Reduced Substantial Improvement Requirement: For rural projects, the “substantial improvement” requirement (which generally means investing at least 100% of the building’s adjusted basis into improvements) will be reduced to 50%, making it easier to rehabilitate existing properties.
  • Definition of Rural: Rural QOZs are generally defined as areas outside cities or towns with populations over 50,000 and not adjacent to urbanized areas.
  1. Increased Reporting and Penalties:
  • Expansive Reporting Requirements: Both Qualified Opportunity Funds (QOFs) and Qualified Opportunity Zone Businesses (QOZBs) will face significantly increased reporting requirements. This includes details like the average number of full-time equivalent employees, NAICS codes, and information on residential units.
  • Non-Compliance Penalties: Stiff penalties for non-compliance are being introduced, potentially up to $50,000 for larger QOFs, with higher fines for intentional disregard of reporting requirements. All reports must be filed electronically.
  1. Other Important Changes:
  • Elimination of 2047 Cliff Date (for new investments): For qualifying investments in QOFs made on or after January 1, 2027, the previous December 31, 2047, deadline for selling the investment to achieve the tax-free gain benefit is eliminated. Investors will have the option to step up their basis to fair market value after 30 years.
  • No Forced Exit from OZ Investment: This means investors who hold their QOZ investment for over ten years will not be forced to sell by a certain date to realize the tax-free gain on appreciation for investments made after December 31, 2026.
    It’s important to note that while these changes are largely expected to be enacted, specific details and effective dates can still be subject to legislative finalization. Investors and fund managers should stay informed about the precise language of the enacted legislation to ensure compliance and maximize benefits.

{ 0 comments }

As I mentioned in my previous post, April saw record levels of volatility in the stock market. 

The severe market swings weren’t just a knee-jerk reaction to tariffs, but rather a reaction to major shifts in the global economic landscape.

The global economic landscape is changing in significant ways that require thoughtful adjustments to your investment strategy. Recent trade policies are creating ripple effects throughout the global economy that will impact long-term investment returns.

Key Developments Affecting Your Investments

Shifting International Relationships

The current tariff policies are straining relationships with key allies. These actions, intended to bolster domestic industries, are inadvertently pushing some of our closest partners towards nations that are traditionally considered U.S. competitors. This realignment extends far beyond simple trade balances and affects global capital flows.

America’s Changing Economic Position

For decades, the U.S. dollar’s status as the world’s primary reserve currency has provided our economy with significant advantages, including lower borrowing costs.

 The trade deficit with our trading partners resulted in their accumulating a surplus of U.S. Dollars. These U.S. Dollars were used to buy down U.S. Treasury bonds, pushing down borrowing costs for not only the U.S. Government but also for U.S. home owners, as our mortgage rates are tightly correlated to the yields on 10-year Treasury bonds.

These dollars also found their way into the U.S. stock market helping prop up stock prices.

However, as our relationships with allies become less certain and international trade policies create instability, this privileged position is beginning to weaken.

Foreign investors are becoming more hesitant to invest in U.S. stocks and bonds. 

We saw evidence of this immediately after the tariffs were announced on “Liberation Day”, when long-term yields spiked as foreign holders of US Treasury bonds decided to sell first and ask questions later. 

We also saw a sharp drop in the prices of U.S. stocks as international investors started to trim their exposure. 

For the past decade, global investors and pension funds from Europe, Asia and Australia have all been buyers of U.S. stocks. As a result U.S. stocks trade at much higher multiples than their counterparts in other developed countries. Investors pay 50% more for each dollar of earnings for U.S. stocks than we do for similar non-U.S. stocks. This premium for American exceptionalism was based on 75 years of economic and political stability. However, this perception of stability among international investors is now fading.

U.S. retail investors have stepped in to buy the dip, which has driven a significant recovery in stock prices. 

So while not immediately alarming, this trend poses meaningful long-term risks to our portfolios if left unaddressed.

The Potential Impact on Your Investments

If foreign investment in U.S. assets continues to decline, we can expect:

  • Weaker Dollar: As investors move away from U.S. dollar assets, imports will become more expensive, further driving inflation
  • Higher Inflation: Less demand for U.S. debt will likely lead to higher interest rates and coupled with increased inflation, reduce purchasing power over time
  • Reduced U.S. Market Performance: Lower capital inflows may limit economic growth and lead to underperformance of U.S. markets compared to international alternatives

Recession risks are also increasing. 

The lack of clarity around the trade and tariff policies is preventing businesses from being able to forecast their inventory, spending or hiring needs. 

American Airlines just announced their earnings, and they provided 2 projections for the rest of the year. One in case of a recession, and another without a recession. We are going to see many more companies offer similar projections because they have no visibility. 

Unlike larger businesses, with massive teams of analysts, small businesses do not have the man power to project multiple scenarios, nor do they have the liquidity or credit lines to survive extended periods of uncertainty. There are over 30 million small businesses in the US who will feel the pain of tariffs, higher interest rates and an economic slowdown. They will be more affected by a recession than the larger companies.

If we do enter a recession, we are likely to see considerably more volatility in the stock market for the remainder of the year.

Our Recommended Strategy Adjustments

To protect and grow your wealth in this evolving environment, we have:

  1. Increased cash allocations: In the short-term, we have been raising cash every time the market rallies. This will be reallocated to short-term treasuries, private credit funds and other global investments.
  2. Increased Global Investments: We’re strategically adding more international developed and emerging market assets to your portfolio. These regions offer strong growth opportunities, appealing valuations, and valuable diversification.
  3. Moderately Reduced U.S. Equity Exposure: We’re carefully decreasing your allocation to U.S. stocks. We still maintain significant U.S. market exposure, but at a more balanced level given the changing global landscape. We have also increased allocation to a private infrastructure fund, a thematic investment which is also expected to have lower volatility than the overall market, and a  long-short equity fund as well. The risk of recession is severely heightened this year and a long-short fund will act as a hedge without sacrificing our exposure to U.S. stocks in case we are wrong.
  4. Maintain a short maturity of our bond holdings: We have been avoiding long-term bonds since the beginning of 2022. Most of our bonds have a maturity of under 5 years. This will prevent losses if long-term interest rates rise. We are also allocating to private credit funds, with maturity under 3 years but higher yields in the 8-10% range
  5. Tax Loss Harvesting opportunities: We will continue to actively seek tax loss harvesting opportunities to potentially lower your annual tax liability. This involves strategically realizing investment losses without altering your current asset allocation. By offsetting taxable capital gains, this process aims to improve your overall tax efficiency.

This strategy shift is not a reaction to short-term market movements but rather a thoughtful response to structural changes in the global economy. Our fundamental goal remains unchanged: to protect and grow your wealth over the long term.

Next Steps

If you have any questions about these changes and how they specifically affect your portfolio please don’t hesitate to reach out to discuss your individual situation. I’m committed to helping you navigate these changing economic conditions with confidence. 

As always, keep calm and invest,

Nirav Desai

Risk Discloures: This is general information is not to be considered investment advice. Any investment included in this email whether, stocks, bonds, alternative assets, cryptocurrencies or commodities may not be suitable for all investors. Please consider your risk tolerance and talk to your advisor before making any decisions based on this email.

{ 0 comments }

Staying the Course Amidst Market Volatility

The financial markets have certainly been making headlines this week, with some sharp movements that might feel unsettling. I wanted to offer a bit of perspective during this period.

The past 7 trading days all saw dramatic intraday moves on the S&P 500, with sharp 4-6% declines coupled with a whopping one-day 9.5% increase as well. 

At one point, the market was down 20% from its recent peak in February. 

While the daily volatility can be scary, it’s important to remember that true market “crashes” – events that fundamentally alter the long-term trajectory – are actually quite rare. 

What we are currently experiencing is a significant dip, to be sure, but one that is not without precedent. The scale of these movements is similar to what we navigated during the initial stages of the Covid-19 pandemic. We also saw similar volatility during the 2008 financial crisis.

Each time, the market has recovered even though it was hard to live through these scenarios.

The main takeaway is to step back and look at the bigger picture.

Your financial plan has been specifically constructed to weather periods like these.

A cornerstone of our strategy is diversification. 

Your investments are carefully spread across a mix of shares (representing ownership in companies), bonds (representing loans to governments and corporations), and other asset classes. This deliberate diversification means that your portfolio is not entirely reliant on the performance of any single market sector. When one area experiences a downturn, others can provide a degree of stability and help to cushion the overall impact.

Furthermore, the very structure of your financial plan is a reflection of your individual circumstances, particularly your proximity to retirement. For those of you nearing retirement, a greater portion of your portfolio is strategically allocated to lower-risk assets, such as government bonds. These types of investments tend to hold their value, and in some cases even appreciate, during periods of stock market downturns, providing a crucial layer of protection when you are closest to needing those funds.

Volatility, while it can feel uncomfortable in the short term, is an inherent characteristic of the market. 

And history has repeatedly shown us that markets do recover. 

In the last 70 years, we have had 8 times when the S&P 500 declined 15% or more in a 30-day period.

In every case, the market recovered within 720 trading days (that’s about 2 years and 10 months), and the average return was 50% at the end of that period.

While the timing and pace of that recovery can vary, long-term investing remains one of the most effective strategies for building and growing your wealth over time. Trying to time the market during these swings is often a recipe for missing out on the eventual rebound.

I understand that these periods can raise questions and even anxieties. Please know that we are closely monitoring the situation and are here to provide clarity and support. In the next post, I’ll discuss some longer-term concerns about the economy and investments, and how to mitigate some of these concerns.

If you have any questions about your portfolio, your financial plan, or simply want to talk through the current market environment, please do not hesitate to reach out. We are always here to offer reassurance and guidance.

Staying informed and maintaining a long-term perspective are your most powerful tools during times like these. Trust in the well-diversified foundation we have built together, and remember that we are here to navigate these market movements with you.

So, as always, keep calm and invest!

{ 0 comments }

Recession is coming

I’m spending the weekend in Whistler, Canada. Although it’s not a holiday weekend, the resort is still fully booked, the ski slopes are busy and people are spending money everywhere.

And yet, after 4 years of looking for signals, and ignoring the the constant predictions from the news media, I finally see signs of an impending recession.

No, it’s not the fact that inflation has started to rear its ugly head, or the threats of tariffs or the crackdown on immigration. While all these factors could individually have a negative impact on the economy, the biggest sign is the stall in the housing market.

Residential construction and home remodeling sector is a significant 4% of the US economy. Its health offers valuable insights into broader economic trends.

Currently, we’re seeing a concerning decline in homes sales and home remodeling spending, approaching levels reminiscent of the 2009 financial crisis.

Imagine the impact in cities where housing costs are already sky-high. In these areas, the construction and remodeling industry is a major economic driver. A slowdown here means job losses, reduced local spending, and a cascading effect on related businesses.

This isn’t just about bricks and mortar; it’s about livelihoods and community stability. The current trend serves as a strong warning sign, suggesting a potential economic downturn that could have far-reaching consequences.

In other words, recession is coming.

For investors, this translates to heightened risk in related industries and a potential dampening effect on consumer spending.Consumer confidence is already declining. It’s down 10% in the past month and 16% in the past year. And when consumer confidence declines, it often leads to lower consumer spending.

When consumer spending declines, business spending and ad spend also declines.

The largest tech companies (the magnificent 7) are highly dependent on business and ad spend. They are over represented in the SP500 – a widely used proxy for the stock market – consisting of roughly 30% of the index.In growth funds, these seven stocks are held in an even higher concentration, as much as 50% or even 75%.

While high-growth tech stocks may have delivered impressive returns in recent years, the current economic climate suggests a potential shift towards greater volatility and increased downside risk.

These stocks are also considerably more overvalued compared to the rest of the stock market, and face a more drastic decline in price.

In fact, this year they have underperformed, especially against international stocks which have finally started to show some signs of life.

In light of these emerging headwinds, particularly within a sector sensitive to interest rate fluctuations and consumer confidence, a prudent approach is warranted.

But not too worry, a good defense is a well diversified portfolio with uncorrelated asset classes. And a focus on stable, established companies with strong fundamentals is crucial in navigating this period of uncertainty.

The housing sector’s decline serves as an early warning, and that a proactive, risk-aware strategy is essential.This is the time to be cautious and look at a defensive strategy.

In client portfolios, I will be slightly lowering our exposure to US public equities, replacing them with private infrastructure companies.

The US needs $1-2 trillion of spend to update our roads, bridges, ports, airports, communications and electrical infrastructure over the decade. A lot of these companies are private, and are trading at cheap valuations.

If not a client and you have one of these situations:

* over-concentrated in high-growth stocks

* have more than 25% of your networth in one stock

* are 5 years from retirement, or

* just generally worried about your financial future

Let’s discuss how these trends may impact your portfolio and explore strategies to mitigate potential risks.

So, as always, keep calm and invest!

Regards,

Nirav

{ 0 comments }


Are you looking to diversify out of concentrated stock positions without the burden of capital gains?

If so, there’s an innovative strategy that might be the perfect fit for you: the 351 exchange.

This strategy allows you to contribute shares of a single stock, along with other shares or ETFs that have capital gains, in exchange for shares in a new ETF.

This approach offers several key benefits:

No Capital Gains: This strategy doesn’t trigger taxes on the gains.
Diversification: Seamlessly transition from a concentrated stock position to a diversified portfolio.
Immediate Liquidity: Unlike traditional 721 exchange funds, there is no seven-year lock-up period.
Cost Efficiency: Enjoy lower fees compared to other strategies, such as 721 exchange funds, or QOZ funds.

However, there are some constraints to follow:

There are some constraints we need to follow:

  • The % of any individual stock can’t exceed 20%
  • The top 5 holdings can’t exceed 50% 

But there are ways to get around these restrictions. Let’s consider a practical example.

How It Works:

Step 1: Contribute $20k of a single stock and $80k of a broad-based index fund ETF, such SPY. The individual stocks inside the ETF will all count and make sure we don’t exceed the 50% cap on the top 10 largest holdings.

In return, you receive ETF 1 valued at $100k.

Step 2: During the offering cycle, contribute an additional $25k of the single stock and $100k of ETF 1, resulting in ETF 2 worth $125k.

Step 3: During the next offering cycle, contribute $30k of the single stock and $125k of ETF 2 to receive $155k worth of ETF 3. 

Over the multi-step process, you’ve exited out of $75k of a single stock, and used $80k of other stocks/ETFs to end up with $155k in ETF 3.

ETF 3 is expected to be a diversified global portfolio of stocks, designed to replicate a strategy similar to Berkshire Hathaway, using the Shareholder Yield methodology, which combines Dividend Yield and Share Buybacks to invest in quality, cashflowing companies.

You keep your original cost-basis in the stock and ETF(s), but you are now globally diversified and have mitigated your single security/sector concentration risk without triggering capital gains.

This strategy integrates seamlessly into your existing portfolio while offering you the ability to strategically manage your capital gains. 

This process is manual and paperwork-intensive, and the next deadline is approaching quickly (11/30/2024). Although it’s expected to be offered on a quarterly basis, so don’t worry if you miss this opportunity.

If you’re interested in exploring this strategy further, please reach out to me as soon as possible. Let’s work together to optimize your portfolio and manage your capital gains effectively.

This is suitable for accredited investors with capital gains of at least $100k in any single stock.

{ 0 comments }

How Will Trump 2.0 Affect Your Portfolio

As we navigate the evolving political landscape, I wanted to share some insights on how a Trump presidency could impact various financial markets, including U.S. and foreign stocks, bonds, Bitcoin, and the U.S. dollar.

Since the election results last week, there has been a strong rally in US stocks, especially Small-cap stocks. The markets have concluded that a Republican sweep of the Presidency, and House of Representatives and the Senate will be bullish for stocks. 

At least in the short term.

Meanwhile the rates on long-term bonds climbed even while the Federal Reserve cut interest rates again. Over the past several weeks, they’ve cut the short-term rates by 0.75% but long-term rates actually went up 0.75% during this time frame.

The bond market thinks a Republican government will be unable to lower the national debt and is worried about the government’s balance sheet.

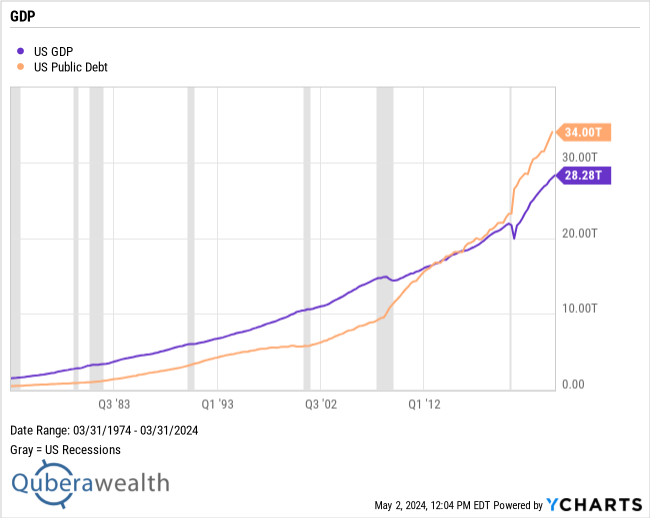
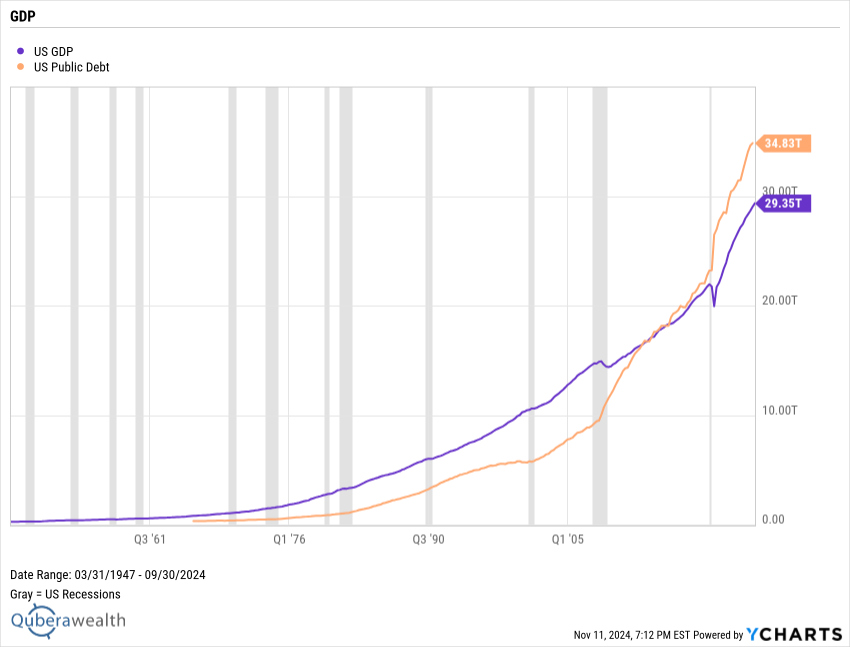
The debt has been increasing at a much faster rate than prior decades, and since Covid, has exceeded the GDP. This is not a good trend.

As our national debt rises so does our interest cost on this debt, which continues to consume a larger portion of our government revenues (i.e. taxes).

Without a reduction in government spending or an increase in taxes (or maybe both), the bond market doesn’t think we can bring our debt back to more prudent levels. Which is why long-term rates are rising – the market wants to get paid more for the risk of holding long-term debt.

It’s highly unlikely the Republicans will raise taxes. Let’s see if they will be able to reduce spending. The bond market is skeptical.

Trump’s pet campaign promises of new tariffs on foreign goods and the reduction/deportation of illegal immigrants are both inflationary. 

Increasing the cost of imported goods is unlikely to make goods cheaper. America’s famously porous border has provided cheap labor for both the agriculture and construction industries. 

Despite the post-Covid spike in prices, our food and housing prices are still cheaper than most other developed countries and Asian countries when compared to their citizens’ income levels.

The rise in long-term rates has negatively affected mortgage rates and the cost of borrowing for many companies. 

Hopefully Trump can figure out how to make housing affordable again.

Over the long-term, this may lead to lower corporate profits and lower consumer spending levels.

Will his campaign promise of lower corporate tax rates offset this? We’ll see.

Another thing impacted by higher rates is the US Dollar. It has strengthened after the election and is likely to stay strong as long as long-term rates stay elevated.

This strengthening of the US Dollar, along with threats of imminent tariffs, has led to a weakening in emerging market stocks and a rather muted rally in foreign developed stocks.

But the difference in valuations between US and non-US stocks is rather stark. In general, investors are paying about 70% more for each dollar of earnings in the US than abroad. 

This disparity will converge at some point. It always does. 

Usually the outperforming asset class will have lackluster performance for several years while the underperforming one rallies hard several years in a row. Getting the timing right is impossible, so we maintain a globally diverse portfolio and rebalance on a regular basis, selling what is overvalued to buy what is undervalued. And we’re getting paid 4%+ in dividends while we wait.

One thing that has really seen a huge boost from Trump 2.0 is Bitcoin.

Everything bitcoin-related was up double digits today (11/8/2024). 

In general, I’m not a fan of cryptocurrencies. They are a solution for a problem that doesn’t really exist. There are many arguments for a decentralized currency but none of them apply to anyone who earns and invests in the world’s reserve currency – the mighty US Dollar.

The only real use case is to avoid income taxes, possibly avoid estate taxes, and defeat currency controls and tracking. 

However, the demand cannot be refuted. Bitcoin ETFs were approved nearly a year ago and have attracted billions of dollars in investor capital – some of it from public pension funds and family offices of extremely wealthy Americans.

The FOMO is real.

And Trump has even announced a Strategic Bitcoin Reserve, which will hold 1 million Bitcoins. This is a terrible idea. Nothing weakens US hegemony like America saying we don’t have faith in our own currency and we want to diversify away from it.

Against this backdrop, my own reservations notwithstanding, I’ve initiated a small position in a Bitcoin ETF in client portfolios. It’s part of our alternative sleeve, which is invested in funds that are expected to be uncorrelated to stocks and bonds. I expect this insanity to continue for a few more months. At that point, we’ll reassess the situation.

Expect the next year to be quite volatile for the stock, bond and foreign exchange markets. 

Despite this, the market’s reaction to a Trump presidency suggests a strong belief in a bullish economic outlook.

So, as always, keep calm and invest!

Please feel free to reach out if you have any questions or would like to discuss this further.

And, as always, keep calm and stay invested.

Nirav

{ 0 comments }

Get ready for higher taxes…

Hope you’re all ready to unwind and have some fun planned for the Memorial Day Weekend.

Not to throw a wet blanket on your fun plans, but I did want to bring to your attention some factors that are going to impact your future tax liability.

Rising National Debt

For decades the national debt was less than the GDP and both were growing at a similar pace. 

Since 2010, the national debt has grown at a much faster rate than the GDP. It reached 100% of GDP in 2019 and has started to grow exponentially since Covid.

This rate of growth is unsustainable. 

And government expenditures are not expected to slow anytime soon. 

Taxes will need to be raised to bring down some of this debt. (Unless we let inflation erode the value of this debt, something the Federal Reserve is fighting hard against).

Over the long term, the trajectory for tax rates is higher. It might not happen overnight, but higher taxes are coming. I believe they will stay higher for longer.

This will happen regardless of who gets elected.

And in the near time, taxes are already set to go up. Even if Congress does nothing. (Or especially since Congress isn’t likely to do anything).

Tax Cuts and Jobs Act (TCJA) Sunsetting 

The Tax Cuts and Jobs Act of 2017 included provisions with temporary tax relief. Many of these individual income tax benefits are set to expire in December 2025. This will result in higher tax bills for most taxpayers. For those in the highest tax bracket, the top rate will go from 37% back to 39.6%.

Estate Tax Limits Sunsetting

Under the TCJA, the current estate tax limit was doubled. Currently estates under $13.6m for individuals, or $27.2m for couples are not subject to the estate tax, which can easily get to 40%.

This higher limit is set to expire at the end of 2025 and the limits are going to get cut in half.

It’s expected these limits will go down to $7m for individuals and $14m for couples.

While this is more than enough for most people, if you already own $10m in assets and expect to live another 20 years, or own $5m and expect to live another 30 years, there is a good chance your estate will have to pay a 40% tax on part of your assets.

It’s the government’s last chance to get one more bite of the apple. 

Net Investment Income Tax(NIIT)

For married households who file jointly and make over $250,000 a year, there is an additional 3.8% NIIT on interest income, dividends, capital gains, real estate and other passive income, royalties and non-qualified annuity income.

For married filing single filers, and single filers, it kicks in at a lower level. $125,000 and $200,000 respectively.

This is not indexed for inflation and will start to ensnare more and more people. A sneaky tax hike that no one pays attention to.

California Tax Increases

For those of you lucky enough to live in California, the disability insurance tax (part of payroll tax) of 1.1% used to be limited to the first $158,000 of income. As of 2024, the cap expired quietly. All wage income will now be taxed.

California also levies a 1% mental health services tax on income exceeding $1 million.

This brings the top rate in California to 14.4%.

If you’re in a high tax bracket, your top bracket (federal + state) is now 51.4%.

That’s what you’ll pay on short term capital gains too. For the past year, we were all excited about the 5% we were earning in Money Market accounts. Now we find the after-tax returns are under 3%. 🙄

Long term capital gains are taxed at a lower rate, but you’ll still pay up to 38.2%. 

Luckily, there is no estate tax in California. 🤯

And social security benefits aren’t taxed either.

What You Can Do:

If you’re a high-tax earner, or have large one-time capital gains from sale of a highly appreciated asset, there are few ways to mitigate some of the tax bite. 

If your estate is likely to be higher than the estate tax limits, there are some strategies we can look at as well.

The first step is to analyze your current tax situation and see where you are.

Schedule a Consultation: We’ll discuss your individual circumstances and explore potential tax-saving strategies.

I’ll also send you a link to upload your tax return directly into my tax analysis software. This will generate a tax report that will give us a basis from which to work from, optimizing the value of any tax deductions or credits and giving you a sense of how much you could potentially save through tax planning strategies.

By planning ahead, we can minimize the impact of potential tax increases and ensure you are utilizing all available tax-saving opportunities.

I will continue to monitor tax policy developments and keep you informed of any significant changes. In the meantime, please don’t hesitate to reach out if you have any questions or concerns.

Sincerely,

Nirav

{ 0 comments }

2023: The Year in Review

2023 was a year that kept us on our toes, to say the least. The stock market delivered a wild ride, with soaring peaks and nerve-wracking dips.

It was quite the rollercoaster and we navigated headlines that felt like chapters straight out of a thriller.

• The war in Ukraine continued for second year
• Multiple major banks collapsed triggering a brief panic, and reminding us of the dangers of keeping too much money in any one bank account
• 86% of economists and 100% of talking heads on TV spent a 2nd year predicting a recession (Why? Because fear sells)
• The yield curve remained inverted all year, an ominous sign of recession
• Despite weakness in some sectors such as technology and real estate, there was no recession, mainly due to strong consumer spending and low unemployment
• War broke out in the Middle East
• The US government nearly shut down over the debt-ceiling crisis, and the US speaker crisis
• The US government didn’t shut down after all
• US housing market refused to crash despite 8% mortgage rates
• The US office market is actually in deep recession, and office buildings in major metros sold at 30-50% discounts to prior sales
• Federal Reserve Chairman, Jay Powell, spent most of the year claiming rates would remain elevated for a long, long time as he was fighting stubborn inflation
• Inflation declined from the peak of 9% and core inflation numbers are now around 3%
• Last month, Jay Powell suddenly claimed victory over inflation and suggested there may be three interest rate cuts next year
• Long term interest rates declined in the second half of the year
• In the past two months every major asset class saw a huge rally

It was a year that tested our resilience, and also highlighted the importance of strategic planning and a calm head amidst the frenzy.

Amidst all this panic and excitement a lot of investors fled the volatility of stock market and instead basked in the comfort of 5% money market funds.

However, money market funds and CDs were one of the year’s worst performers, eclipsed only by long-term bonds.

Cash: 4%
90-day Treasuries : 5.2%
Aggregate Bonds : 5.1%
Intermediate Treasuries: 3.2%
Long-term Treasuries: 1.4%

Gold: 13%
Global REITs: 9.6%

US Large-cap stocks: 25%
US small cap stocks: 17.9%
US Tech stocks: 54%
International Stocks: 17.6%
Emerging Market stocks: 8%

As is often the case, risk assets provided much better returns than CDs.

Looking ahead, 2024 promises to be just as exciting and dynamic. While predicting the future is always a fool’s errand, I remain optimistic about the opportunities that lie ahead. We’ll keep a close eye on the markets, analyze the evolving economic landscape, and work diligently to ensure our financial plans stay on track.

As we raise a glass to the New Year, let’s take a moment to acknowledge the hard work we’ve all put into our financial goals. Whether it was saving for a dream home, planning for retirement, or simply building a more secure future, every step we took, big or small, mattered. Remember, financial progress is a marathon, not a sprint, and every milestone deserves a moment of celebration.

As always, my inbox is always open. If you have any questions, concerns, or simply want to talk about your financial goals, please don’t hesitate to reach out. I’m here to support you on your journey to financial success.

In the meantime, I wish you and your loved ones a joyous and prosperous New Year filled with health, happiness, and continued achievements. Let’s raise a toast to the year that was and embrace the adventures that await in the year to come.

{ 0 comments }

2022: The Year In Review

2022 was a year for the record books.

From an investment standpoint, it was pretty bad. Almost every asset class was down, and most of them were down double digits. 

We saw the Russian invasion of Ukraine leading to the complete removal of Russian stocks from Emerging Market Stock Indices. 

The UK bond market came unhinged and had to be bailed out by the Bank of England after threatening to create massive defaults in British pensions.

The Pound and the Euro saw the sharpest declines against the US Dollar ever.

US treasuries, which are usually considered safe havens during market declines weren’t spared either, as the fastest rate hikes in history raised interest rates from near zero in January to about 4% before the end of the year.

Mortgage rates doubled from 3.5% at the beginning of the year to nearly 7% at the end. The real estate housing market is frozen for now, but prices are softening across the board.

After decades of absence, inflation finally popped up and proved anything but transitory. The much-hyped Treasury Inflation-Protected Bonds (TIPs) didn’t provide as much of an inflation hedge as expected and were still down, although they performed slightly better than equivalent Treasuries.

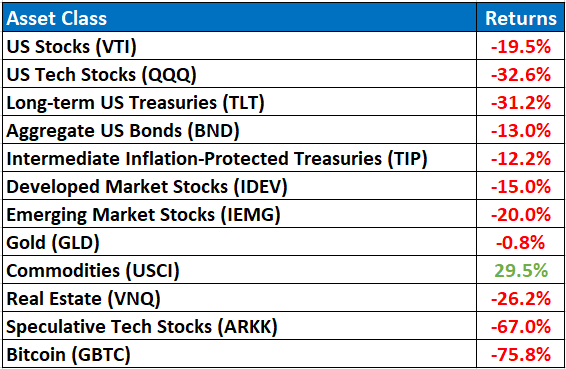
The only positive asset class was commodities, being up about 30% as a group. In the face of the strengthening US Dollar, this outperformance is quite remarkable.

But even Gold, considered the ultimate safe haven, was about flat for the year.

And we saw the collapse of cryptocurrencies and the speculative tech trade. 

Here are the returns for the most common asset classes, and their accompanying ticker symbol:

The worst performers were Speculative Tech stocks and Bitcoin, both of which were crushed in 2022 after seeing eye-popping triple-digit returns in 2020 (150% and 290% respectively).

High-flying stocks of yesteryear such as Tesla, Peloton, Rivian, NVIDIA, Netflix, and Zoom Video Communications all got crushed as their astronomical valuations finally caught up with them.

The more overvalued a stock was, the larger the losses.

That’s one inescapable fact of investing. Prices need to match valuations. When you ignore valuations and chase price performance, it eventually ends in tears and large losses.

Luckily, my portfolios are designed with value in mind. My clients and I weathered the storm with average losses between 12% and 15%. 

Hedging our sensitivity to interest rates, and overweighting high-quality stocks with real earnings and cash flow helped prevent major losses. Exposure to commodities and gold helped offset our losses from real estate investment trusts. And further hedges helped buffer some of the losses in foreign markets.

Losing money is always painful, but all in all, it wasn’t as bad as it could have been.

And remember, the math of returns is geometric. 

The more you lose in a bear market, the harder it is to catch up to breakeven.

It’s much easier to make 10% a year than it is 50%. The more you lose, the more risk you need to take in order to get back to breakeven.

Unfortunately taking more risk doesn’t guarantee a higher return – just a higher variance in the outcome. While you might make more money, you could also lose more money. This became painfully apparent to all the spec-tech & Bitcoin traders of the past few years.

This is why I prefer clients go through the financial planning process before we actually invest their money. Once you understand how much money you actually need to achieve all your goals in life, and we’ve qualified and quantified those goals, we should take the least amount of risk needed.

Yes, risk and return go hand in hand. There is no return without risk.

But the nature of risk is such that sometimes the return doesn’t show up when we need it. So, one should always focus on the potential risks, and not the potential returns.

Managing risk is much easier than managing returns.

Going into 2023, calls for a recession are rampant. Anytime I turn on CNBC, someone is calling for a recession. 2/3rds of surveyed economists predict a recession this year. 

If this comes true, it will be the most widely expected recession in the history of mankind!

If you think everyone is extremely pessimistic on TV, you’re better off tuning them out.

Excessive pessimism makes you sound intelligent and making outlandish claims gets you more airtime on TV. After a while, no one remembers your claims so there’s no one to hold you accountable. But you do get a lot of free publicity, which leads to more recognition and interviews, and this eventually leads to more clients and more money. 

But if you’re always pessimistic, your returns will be lackluster.

Personally, I think recession fears are overblown.

Despite all the talking heads on CNBC who keep shouting that the Federal Reserve will trigger a recession with too many rate hikes, and a recession is mandatory to curb inflation, I think the underlying economy has shown it’s quite resilient and a recession is not guaranteed.

Any recession we might see could likely be short-lived and mild.

That being said, I think inflation is likely to stay higher than the targeted 2%.  Probably closer to the 3-4% range for the next decade. That’s a bigger concern to me than a mild recession.

There are 3 major inputs in inflation calculation: goods, housing, and services (or labor).

The prior 30 years saw peak globalization, with just-in-time inventory and cheap overseas labor putting a lid on inflation in the cost of goods. A strong dollar also helped with this, especially in the last decade. These trends are reversing, and the current focus is on reshoring or bringing manufacturing back to the US, resulting in higher costs. 

There is currently a massive shortage of housing across the US. With interest rates at 7%, affordability has tanked and resulted in a sharp decline in home sales. This will likely trigger a recession in the housing sector. But the lack of supply will provide a floor under this, unlike the 2008 recession where supply far-exceeded demand. Once interest rates stabilize later this year, it’s likely mortgage rates will come down to a more manageable 5%, and home building and sales will pick up again. But the sub-3% rates are gone for good, so expect a resetting of home prices at some point in the near future.

The cost of services is driven by wages, and they’ve seen a sharp rise in the past year. Especially at the lower levels of society. While tech companies are announcing layoffs at the corporate level, many blue-collar jobs are seeing a shortage of workers and commanding top dollar. 

I recently paid an electrician $100/hour for work around the house. He was the 5th person I’ve tried to hire. The previous 4 either never showed up, or ghosted me after the initial contact. Tradesmen are busy and have more work than they can handle.

Why is inflation a bigger concern than a mild recession?

If inflation is 4% over the next 10 years, the value of your savings drops 34%. Based on the past 20 years of historical data, where inflation ranged under 2%, the value of your savings only dropped 18%. A lot of online models still use this low 2%, which means there will be a shortfall retirement savings.

On the flipside, a mild recession is likely to be short-lived and have less of a financial impact.

Despite the chance of recession and higher inflation, I will be lightening up on my hedges this year. There’s no free lunch in investing. Hedging comes at a cost. When you hedge excessively, you pay a heavy price in the form of lower returns over the long term.

Lower returns are the price you pay when you hedge against volatility.

If you can’t accept volatility, then you must accept lower returns. 

Otherwise, you can lower your risk by buying undervalued assets and avoiding overvalued or speculative assets.

After a decade of underperformance, I think foreign stocks will finally start to outperform US stocks. They are at historically and relatively low valuations and provide excellent entry points.

Bonds are also finally seeing a relatively high yield and are no longer a “returnless risk” asset.

Regardless of whether this year sees a continuation of 2022 or a rebound in asset prices, remember price is what you pay, value is what you get. If your investment horizon is long, and you are still in the accumulation phase, you will want stock prices to be cheap for as long as possible. 

I wish you all a very happy and prosperous new year!

And, as always, keep calm and stay invested.

Regards,

Nirav

{ 0 comments }